Broker Industry & Commissions 3 min read 33 views

How Mortgage Brokers Get Paid in Australia: Upfront Commissions, Trail & Clawback Rules (2026)

A transparent look at how Australian mortgage brokers get paid, explaining upfront fees, trail commissions, clawback periods, and the Best Interests Duty.

How Mortgage Brokers Get Paid in Australia: Upfront Commissions, Trail & Clawback Rules (2026)

With over 74% of all Australian residential mortgages now originated through mortgage brokers, understanding how brokers are remunerated, how the Best Interests Duty (BID) protects consumers, and how clawback mechanics operate is essential for both borrowers and finance professionals.

Broker Remuneration Executive Summary
  • Upfront Commission Benchmark: Lenders pay an average upfront commission of 0.65% (+ GST) of the net settled loan balance after deducting any offset account balances.
  • Ongoing Trail Commission: Lenders pay an ongoing trail commission of approximately 0.15% (+ GST) per annum based on the reducing balance of the loan, incentivizing ongoing customer care and annual rate reviews.
  • ASIC Best Interests Duty (BID): Under Part 3-5A of the National Consumer Credit Protection Act 2009, brokers are legally bound to act in the best interests of the consumer. Bank branch loan officers are legally exempt from this requirement.
  • Clawback Provisions: If a borrower discharges, refinances, or sells their property within 12 to 24 months of settlement, the lender clawbacks up to 100% of the upfront commission paid to the broker.
Average Upfront Fee
0.65% + GST
Paid by lender upon settlement
Ongoing Trail Fee
0.15% p.a.
Paid on reducing loan balance
Broker Market Share
74.1%
National home loan originations
Cost to Borrower
$0 (Free)
100% lender funded

1. The Regulatory Contrast: Broker BID vs. Bank Branch Lending

A crucial consumer protection distinction often overlooked by borrowers is that a bank loan officer working directly at a branch only sells their own bank's products and owes no statutory duty to recommend a better rate elsewhere.

In contrast, licensed mortgage brokers operate under ASIC Regulatory Guide RG 273: Mortgage Brokers: Best Interests Duty. Brokers must document comprehensive loan comparisons across an extensive lender panel, demonstrate why the chosen loan product is superior for the borrower's circumstances, and disclose all fee structures prior to submission.

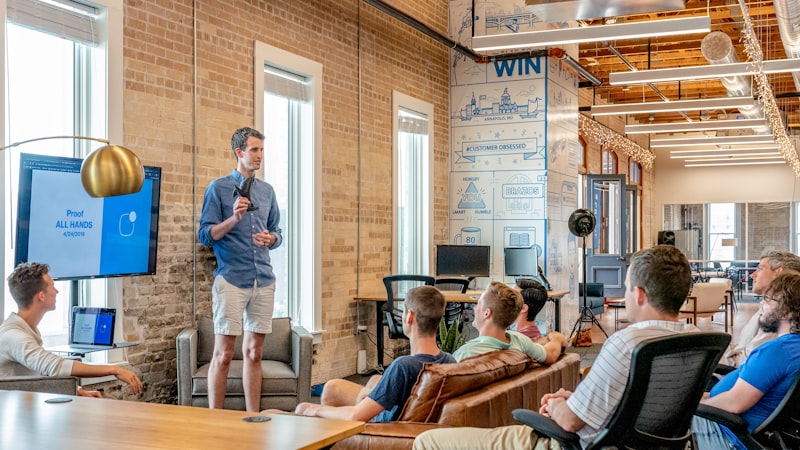
Professional mortgage broker consultation and customer relationship
Australian mortgage brokers compare dozens of lenders under statutory Best Interests Duty laws. Picture: Supplied / Owly

2. The Clawback Mechanism: How Lenders Manage Churn

To protect wholesale lender capital against excessive loan refinancing churn, banks enforce contractual clawback policies with brokers:

Discharge Timing Window Lender Clawback Percentage Impact on Broker Remuneration
Months 0 to 12 100% Clawback The lender demands 100% of the upfront commission be repaid in full.
Months 13 to 18 50% Clawback The lender recoups half of the original upfront commission payment.
Months 19 to 24 25% Clawback Partial recovery depending on specific bank lender schedule agreements.
After Month 24 0% Clawback (Free) Loan is seasoned. Broker retains all commission and can review terms freely.
Mortgage broker reviewing loan comparison software
Brokers maintain ongoing relationships to review rates annually. Picture: Owly
Finance team collaborating on loan structuring
Lead qualification platforms ensure high client-broker alignment. Picture: Owly

3. Frequently Asked Questions: Broker Commissions in Australia

Do mortgage brokers charge higher rates to earn more commission?

No. Commission rates are largely standardized across lenders (typically 0.65% upfront) and are paid from the bank's wholesale operating margins. In fact, brokers often access exclusive wholesale rate discounts and fee waivers unavailable to retail branch walk-ins.

Can a broker charge the customer a fee?

For standard residential owner-occupier and investment loans, mortgage brokers do not charge clients any fees. For complex commercial transactions, private debt syndications, or unusual short-term bridging finance, brokers may charge an agreed mandate fee disclosed upfront.

Partner with an Accredited Owly Mortgage Specialist

Experience the transparency of Best Interests Duty broking across 40+ leading Australian banks.
Enjoyed this article?
Share:

Comments (0)

Leave a Comment

No comments yet. Be the first to share your thoughts!

Stay Updated

Get Expert Loan Tips in Your Inbox

Join 10,000+ Australians who receive weekly insights on mortgages, rates, and smart borrowing strategies.

Customer Customer Customer Customer
Customer
+5k
Trusted by 5,000+ subscribers
4.9/5 average rating
Discover More

More Articles You Might Like

Handpicked reads from our blog

Explore Loan Options

Find the perfect loan type for your needs

Trusted by Thousands of Australians

Join the growing community who found their dream loans through Owly

100s+
Happy Borrowers
1,000+
Loans Approved
15 min
Avg. Setup Time
4.9/5
Customer Rating

Partnered with Australia's leading lenders

Commonwealth Bank Westpac ANZ NAB Macquarie

What Our Customers Say

Real stories from real borrowers

"Owly made finding the right broker so easy. I didn't have to repeat my story 5 times to different lenders!"
Sarah J.
Sarah J.

First Home Buyer, Sydney

"I saved $150/month on my mortgage by refinancing through Owly. My broker found me a deal I never knew existed!"
James T.
James T.

Refinance, Melbourne

"Finally, a platform that understands both sides. Secure, fast, and actually useful for investors like me."
Lisa C.
Lisa C.

Property Investor, Brisbane

Quick Questions

Common questions answered

Is Owly really free for borrowers?
Yes, absolutely! Owly is completely free for borrowers—no hidden fees, no charges, no obligations. Our brokers are paid by lenders, not by you, so you get expert advice at zero cost.
How long does the approval process take?
Most borrowers get matched with a broker within 24 hours. The loan approval timeline varies by lender, but our brokers work to expedite the process—often achieving pre-approval within 1-3 business days.
Is my personal information secure?
Your security is our priority. We use 256-bit TLS encryption, store data in certified Australian data centres, and never sell your information to third parties. We're fully compliant with the Privacy Act.